
Calcium Hydroxide - China CAS: 1305-62-0
Calcium Hydroxide - China CAS: 1305-62-0

The Hormuz crisis reshaped global fertilizer flows, accelerating growth in North America, India and China. This article examines the top agrochemical suppliers, their market shares, and emerging trends in urea, phosphate and potash distribution.
By 2026 the global ascorbic acid market will still be anchored by China, yet freight cost inflation and new regulatory pressures are reshaping procurement strategies. Companies must navigate logistics premiums, ensure ICs2 compliance, and diversify suppliers to mitigate risk.
India’s polypropylene market is facing supply pressure as feedstock restrictions affect around 80% of domestic PP capacity. Buyers are evaluating imports, alternative suppliers and pricing strategies before further market changes.
In 2026, MAP procurement hinges on Morocco’s expanding export capacity and South Korea’s strategic reserves. Pricing trends show a stable floor driven by feedstock inflation, while seasonal buying risks require careful timing. This guide outlines key market dynamics, supplier insights, and risk mitigation strategies for global buyers.
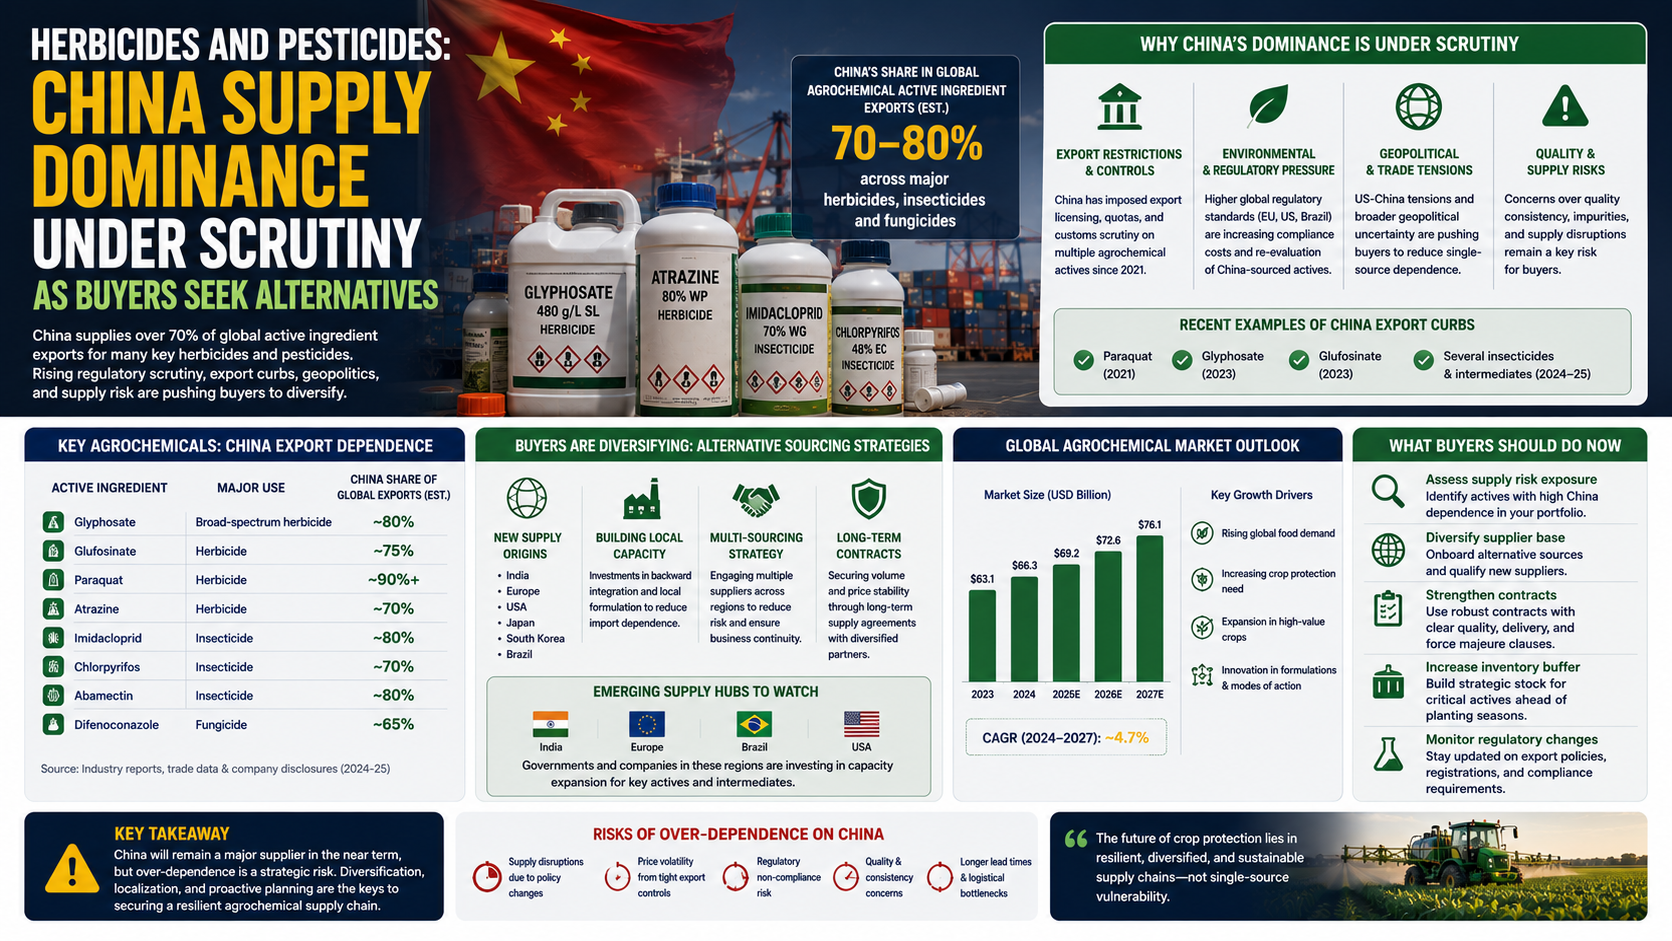
Discover the seven chemicals where China dominates over 70% of global supply, exposing U.S. and EU buyers to tariffs, supply disruptions, and geopolitical risk. Understand the implications for the chemical supply chain and explore strategic mitigation options.
The phosphate supply chain faces tightening margins, export restrictions and volatile MAP and DAP prices in 2026. OCP Group’s strategic moves, phosphoric acid market shifts and global fertilizer sourcing risks shape the outlook. Read on for a deep dive.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.