
1. Hormuz Pipeline Recovery Delays
The ongoing repairs on the Baku–Tbilisi–Ceyhan (BTC) pipeline have been pushed back by an additional 4‑week window, according to the latest OPEC + reports. This setback directly impacts the supply of refined petrochemicals to the EU and Middle East, forcing procurement teams to reassess inventory buffers and explore alternative feedstock routes.
Implications for Buyers
Potential price volatility in ethylene‑derived products.
Increased demand for LNG‑based feedstocks.
Need to secure long‑term contracts with secondary suppliers.
2. Olin‑Huntsman Merger – Final Approval Pending
The antitrust review in the United States is set to conclude on July 10, which could unlock a combined entity with a 22% market share in specialty chemicals. Procurement managers should prepare for possible consolidation of vendor lists and renegotiation of pricing tiers.
3. INEOS Styrolution Expands into Asia
INEOS Styrolution has announced a new styrene‑monomer plant in Vietnam, targeting a 20% increase in regional output by 2028. This development signals a shift in supply dynamics for polymer resins in Southeast Asia.
Strategic Takeaway
Consider sourcing styrene derivatives from the new plant to reduce lead times.
Negotiate volume discounts aligned with the plant’s ramp‑up schedule.
4. Urea Prices Surge – 15% YoY Increase
According to the International Fertilizer Association, global urea prices rose by 15% year‑on‑year, driven by heightened demand from the Asia‑Pacific region and supply disruptions in Brazil.
Mitigation Strategies
Lock in forward contracts with tier‑1 urea suppliers.
Explore alternative nitrogen sources such as ammonia‑based fertilizers.
Implement dynamic pricing models in procurement contracts.
5. ICIS 2026 Forecasts a 3% Drop in Aromatics
The International Chemical Information Service predicts a modest decline in aromatics demand, influenced by a shift towards renewable feedstocks in the automotive sector.
6. New PFAS Regulations in the EU
Effective July 1, 2026, the EU expands its PFAS restrictions to include all perfluoroalkyl sulfonates. Chemical procurement teams must audit current inventories and seek compliant alternatives.
Compliance Checklist
Identify all PFAS-containing ingredients.
Validate supplier certifications for PFAS‑free products.
Update internal material safety data sheets (MSDS).
7. ICIS Predicts a 5% Rise in Ethylene Demand
With construction booms in North America, ethylene demand is projected to climb, affecting downstream polyethylene and ethylene oxide markets.
8. Global Supply Chain Resilience Initiatives
Several G20 countries are launching joint initiatives to diversify critical chemical supply chains. Procurement leaders should monitor partnership agreements for potential new sourcing avenues.
The Bottom Line for Chemical Buyers
This week's intelligence landscape highlights a market that remains highly sensitive to both geopolitical and operational developments. While the Hormuz crisis has entered a recovery phase, logistics bottlenecks persist. At the same time, mergers, insolvencies, regulatory deadlines and weather-related risks continue to reshape procurement priorities.
Organizations that actively monitor supplier exposure, maintain inventory discipline and address compliance requirements before deadlines arrive will be better positioned to navigate the second half of 2026. The coming weeks are likely to reward preparation more than reaction.
Ready to source chemical products from verified global suppliers? Explore competitive offers on our platform today.
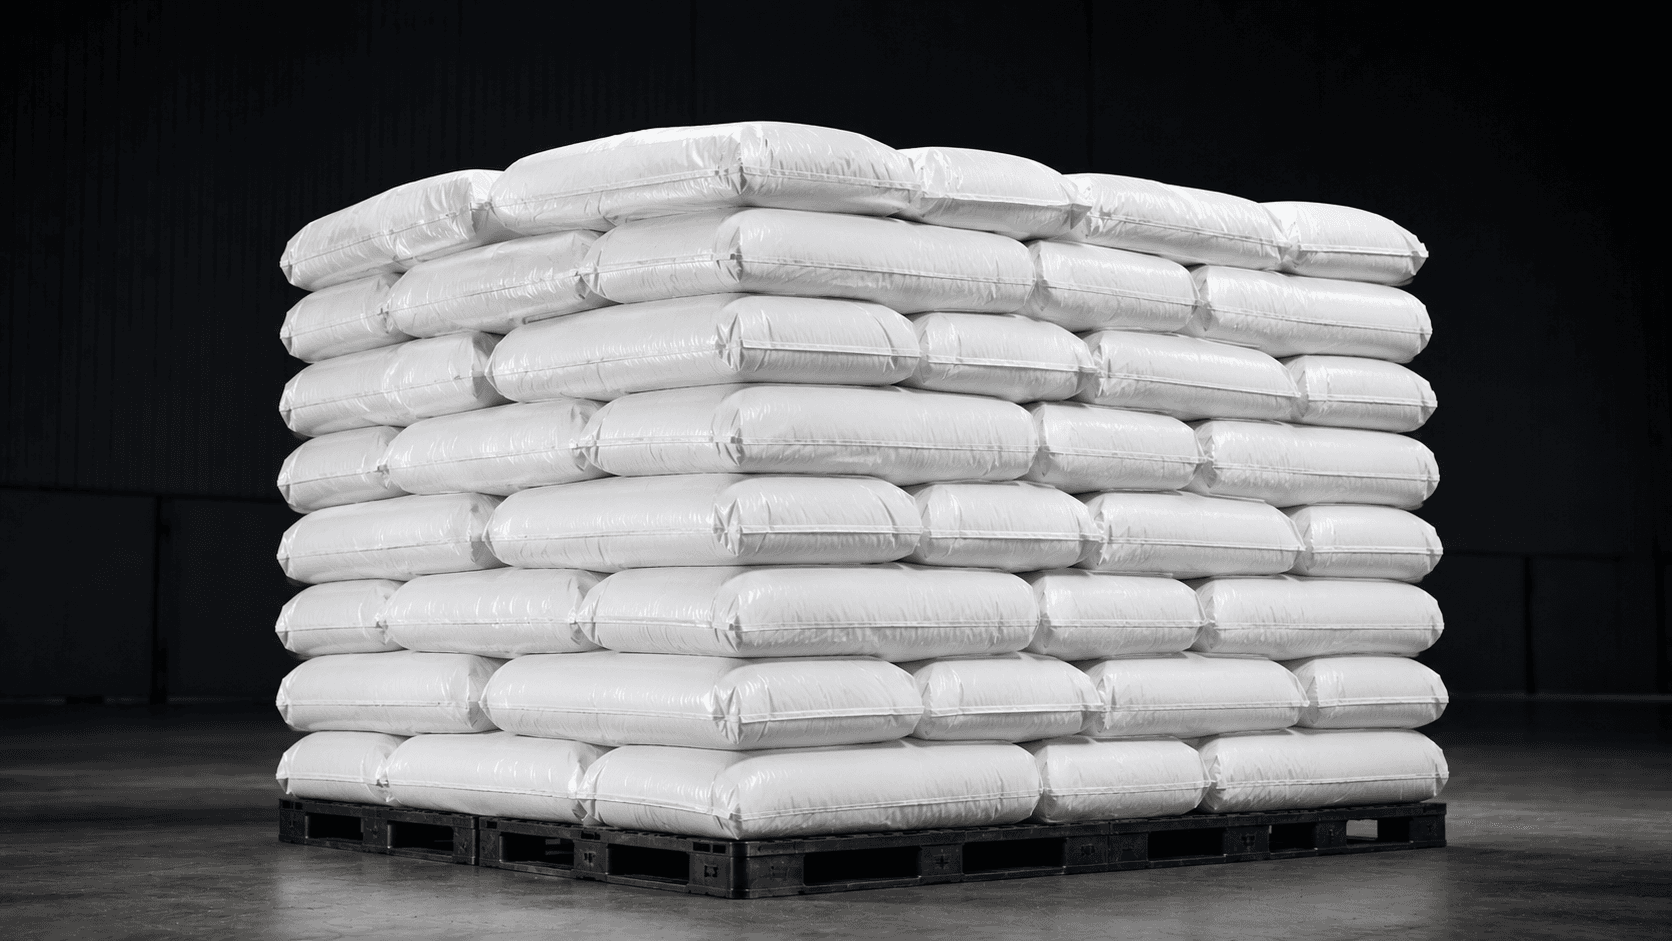
Urea (Granular) - Egypt CAS: 57-13-6