
Urea (Granular) - Egypt CAS: 57-13-6
Urea (Granular) - Egypt CAS: 57-13-6
Pharmaceutical solvent markets are entering H2 2026 with improving feedstock economics and stabilizing crude oil prices. This creates an ideal procurement window for pharmaceutical manufacturers to secure long-term solvent supply agreements before potential market volatility returns.
The global MSG market enters a critical procurement period as major Chinese producers prepare their second half of 2026 pricing. Freight costs have eased, feedstock conditions remain favorable and buyers have a limited window to secure competitive contracts before new price schedules take effect.
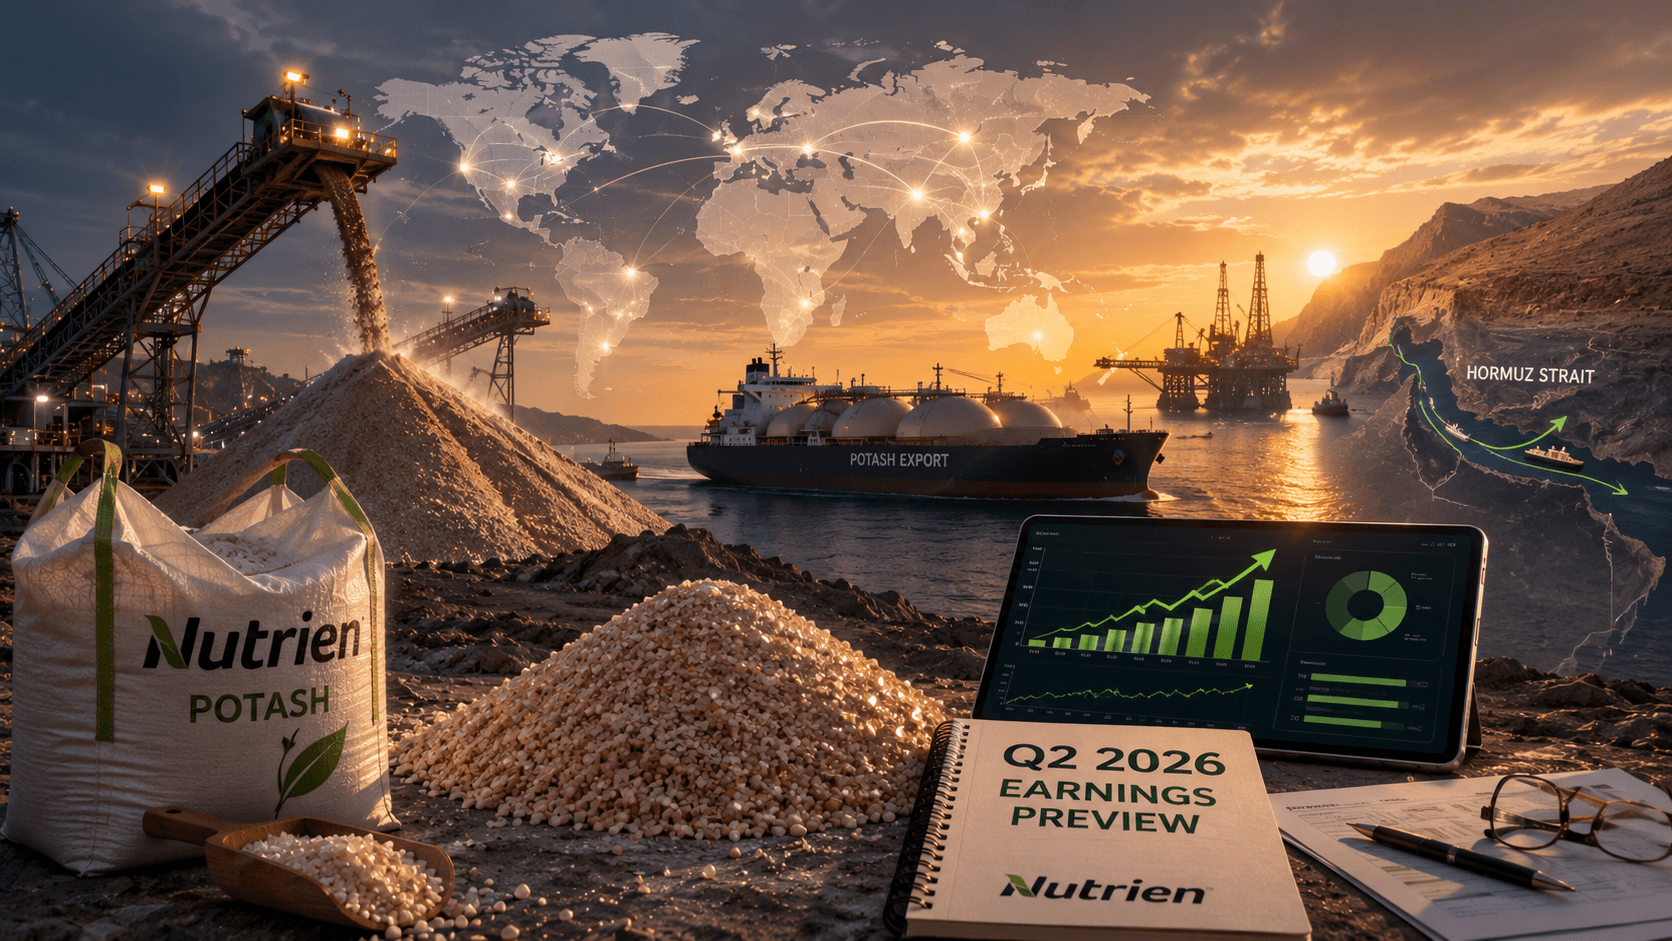
Nutrien is expected to report exceptionally strong Q2 2026 earnings as sanctions on Russian and Belarusian potash combine with Hormuz supply disruption to tighten global markets. Potash buyers should watch July guidance closely before negotiating H2 contracts.
Petrochemical markets are moving toward recovery as Brent prices ease, Hormuz transit improves and supply confidence returns. This outlook explains why price correction may happen slowly rather than through a sharp decline.
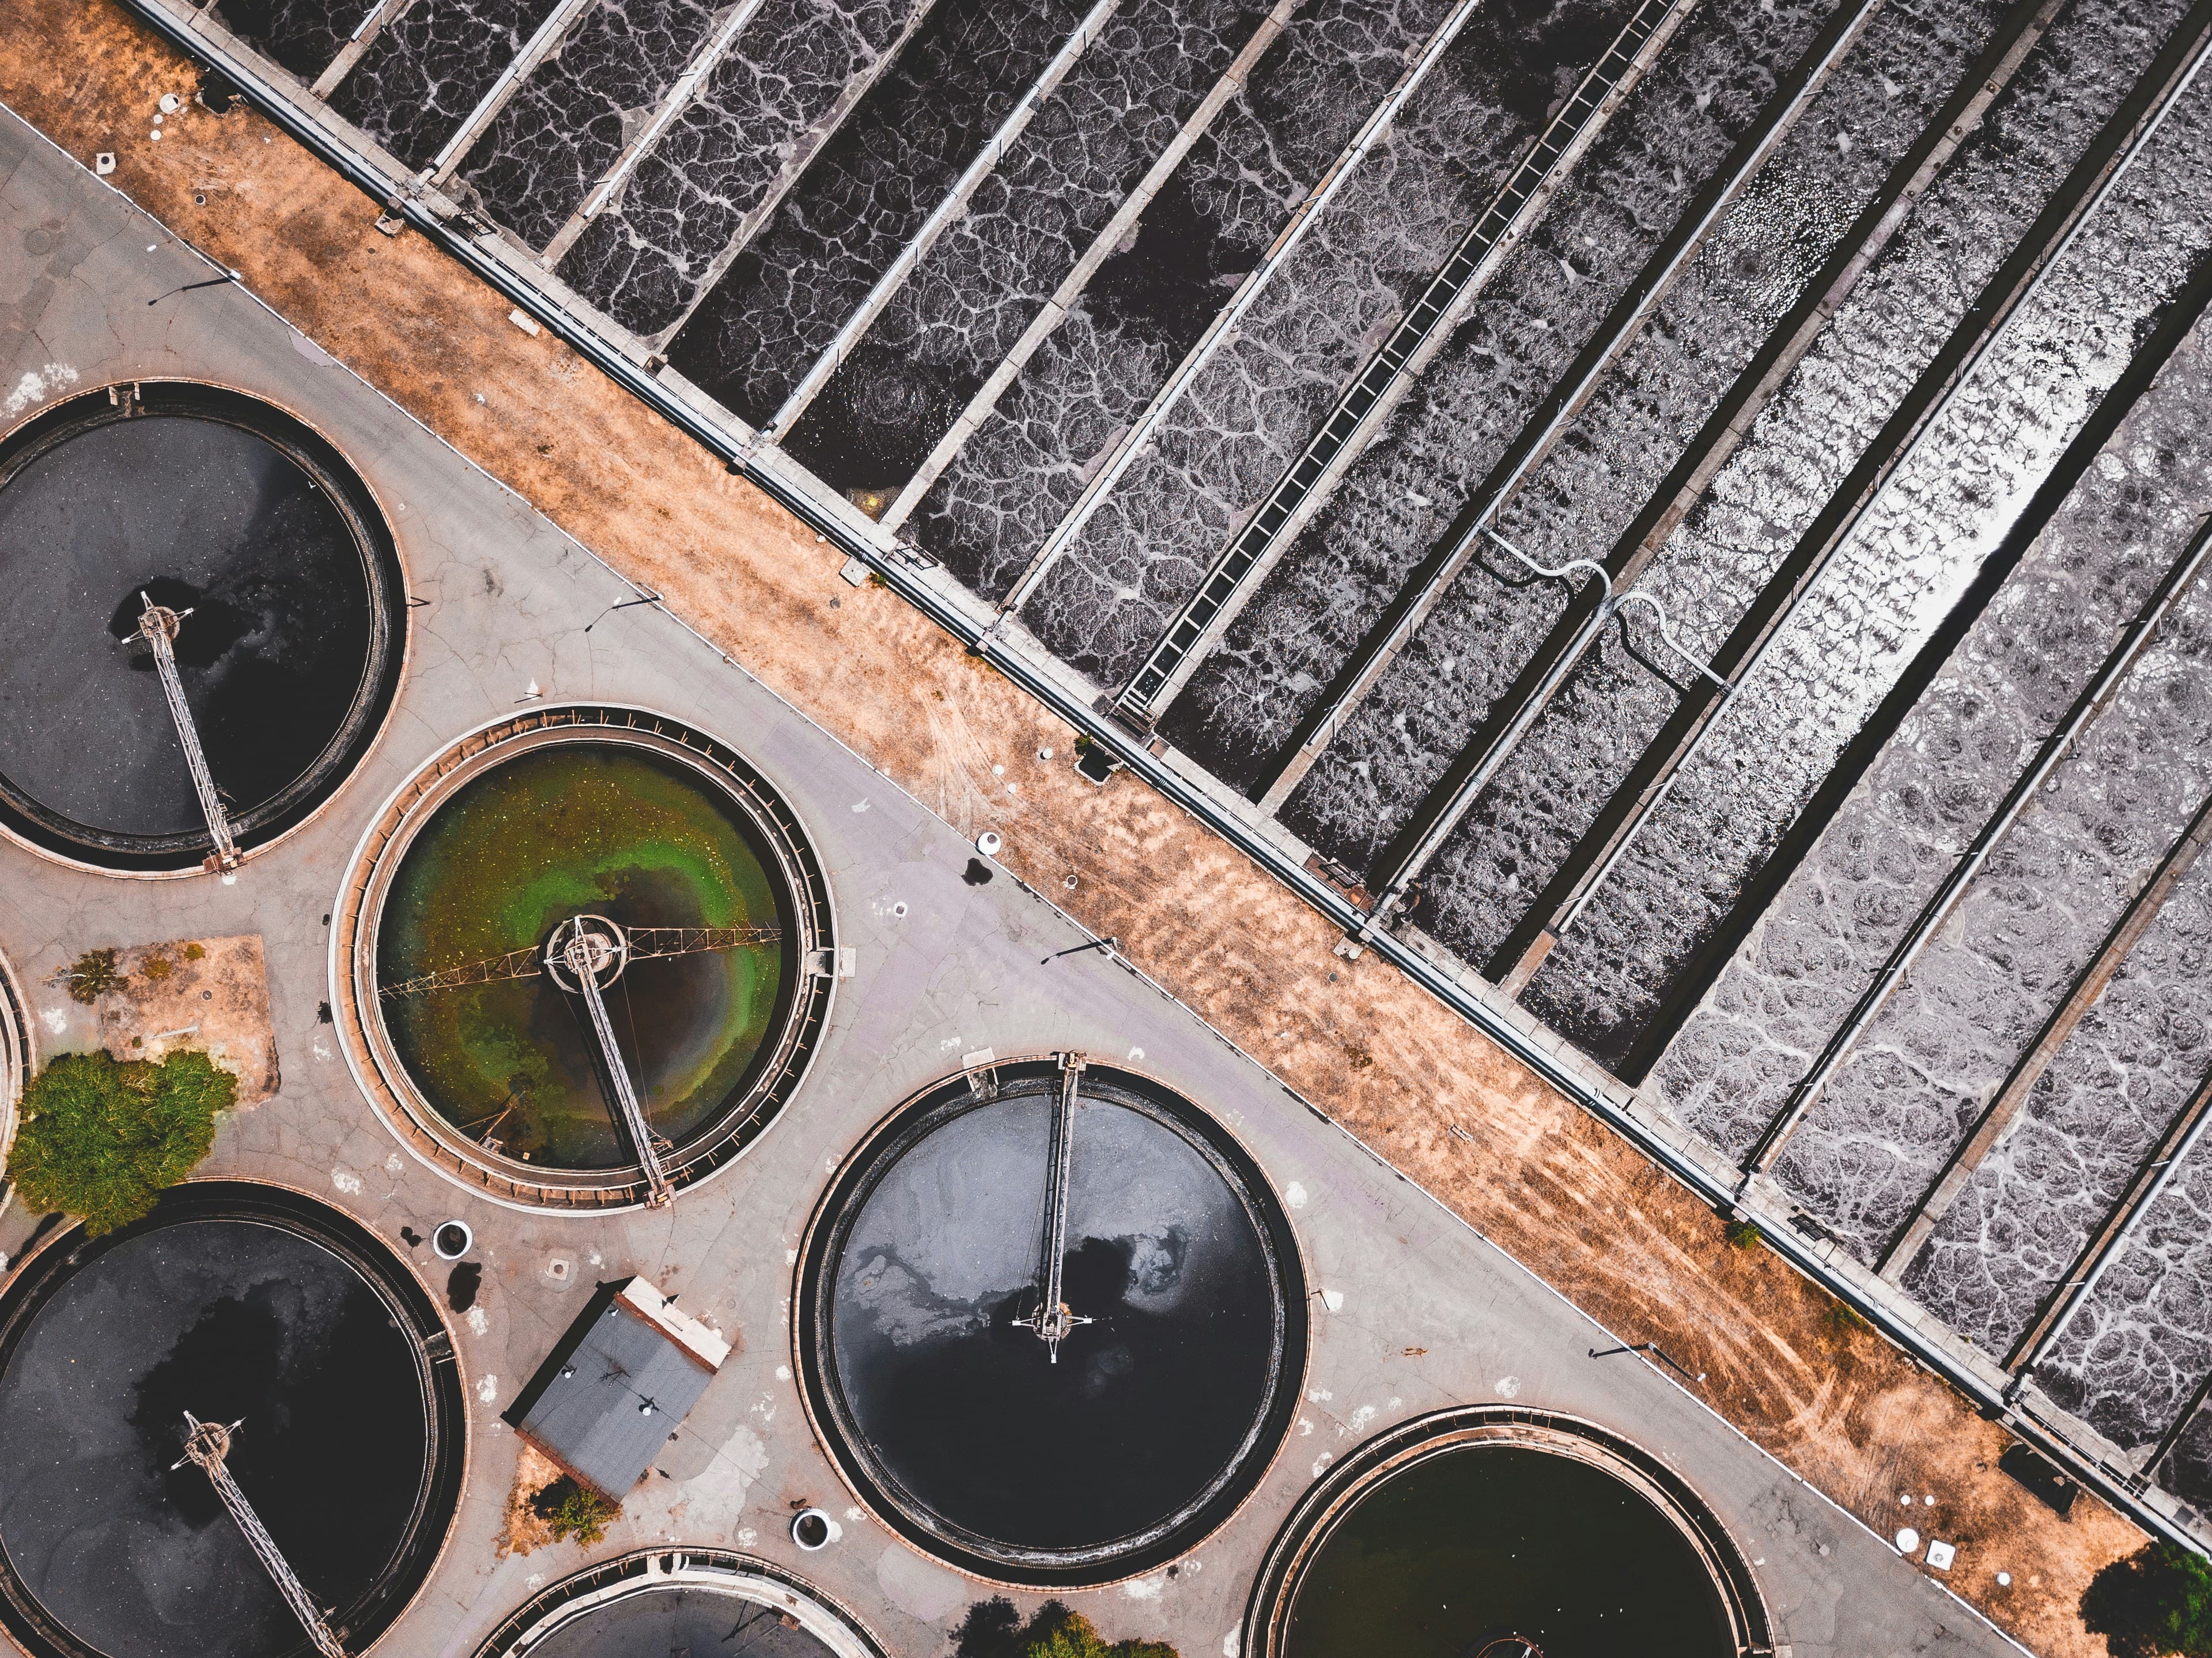
As desalination plants across the GCC return to normal operations following the Hormuz recovery, utilities are rebuilding inventories of critical water treatment chemicals. Demand for PAC, polyacrylamide, sodium hypochlorite, scale inhibitors, and biocides is surging, creating significant procurement opportunities for suppliers serving the Middle East water sector.
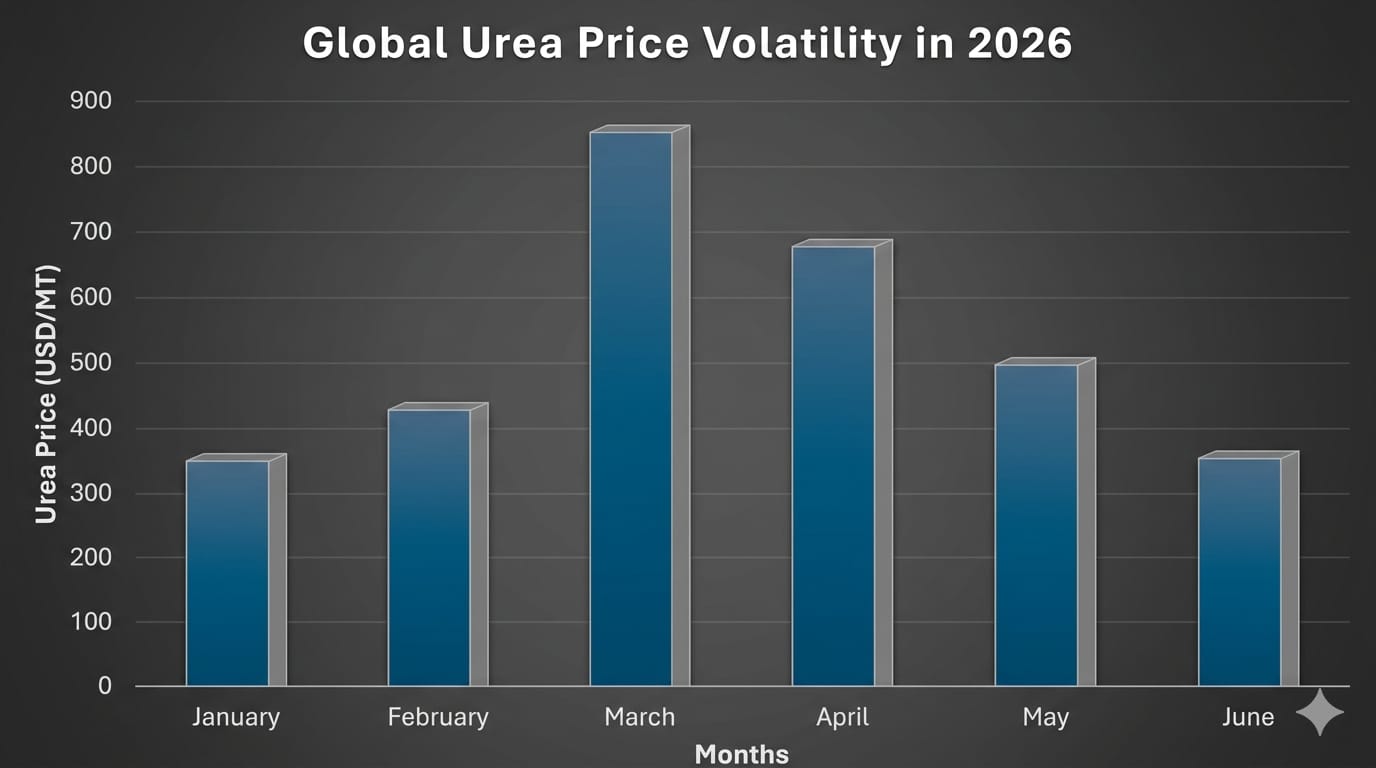
Urea prices have dropped sharply after the Hormuz MOU, creating potential buying opportunities for fertilizer buyers despite ongoing supply recovery challenges.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.