In 2023, analysts predict that China will import a record amount of crude oil due to rising gasoline consumption as more people travel as a result of the removal of COVID-19 regulations and the startup of new refineries.
The issue is cited from Reuters in early 2023. China's crude imports may rise by 500,000 to 1 million barrels per day (bpd) or more this year, reaching as high as 11.8 million bpd, experts from four industry consultancies, including Wood Mackenzie, FGE, Energy Aspects, and S&P Global Commodity Insight, say, this would reverse a decline from the previous two years, and breaking the previous record of 10.8 million bpd set in 2020. The four consultancies predicted that Chinese refineries will boost oil throughput by 850,000 Due to growing local demand and appealing export markets, production is expected to climb to 1.2 million bpd over 2022 levels, or 6% to 9%.
Another positive development for the oil market will be the expectation of robust demand from the largest importer in the world, which will add to the support already provided by the OPEC+ producing group's output cutbacks and western sanctions against Russian shipments.
China has seen an increase in demand for gasoline and jet fuel when COVID limits were removed in December. Sun Jianan, an analyst at Energy Aspects, predicted that gasoline and jet fuel would be the main drivers of the increase in demand for liquid fuels. By the end of 2023, Sun predicted that jet fuel usage would be 90% higher than it was before COVID.
As per FGE analyst Mia Geng and Energy Aspects' Sun, the rebound in China's manufacturing and real estate sectors will take longer to manifest, which will slow down demand growth for diesel, a crucial industrial and transportation fuel, and naphtha, a petrochemical feedstock.
Refiners will be encouraged to increase runs in order to maintain profitable export cargoes and deliver more feedstocks to the petrochemical industry, analysts said, in addition to meeting the growing domestic demand.
Industry sources predict that two new PetroChina-owned refineries, Guangdong Petrochemical and Jiangsu Shenghong Petrochemical, with a combined capacity of 520,000 bpd, would begin functioning commercially in the coming months.
According to a corporate source, a third greenfield refinery, the 400,000 bpd Shandong Yulong Petrochemical facility, may start importing crude towards the end of 2023 in preparation for potential test runs.
Experts did list several reasons to be wary of demand projections despite all the favorable elements. External hindrances, such as a bleak outlook for the world economy, would put stress on China's export industry. The potential for a COVID virus return and the uncertainty surrounding China's fuel export policy were listed as additional risks by analysts.
References:
Aizhu, Chen & Xu, Muyu. 2022. China set for record crude oil imports in 2023, analysts say. Reuters.
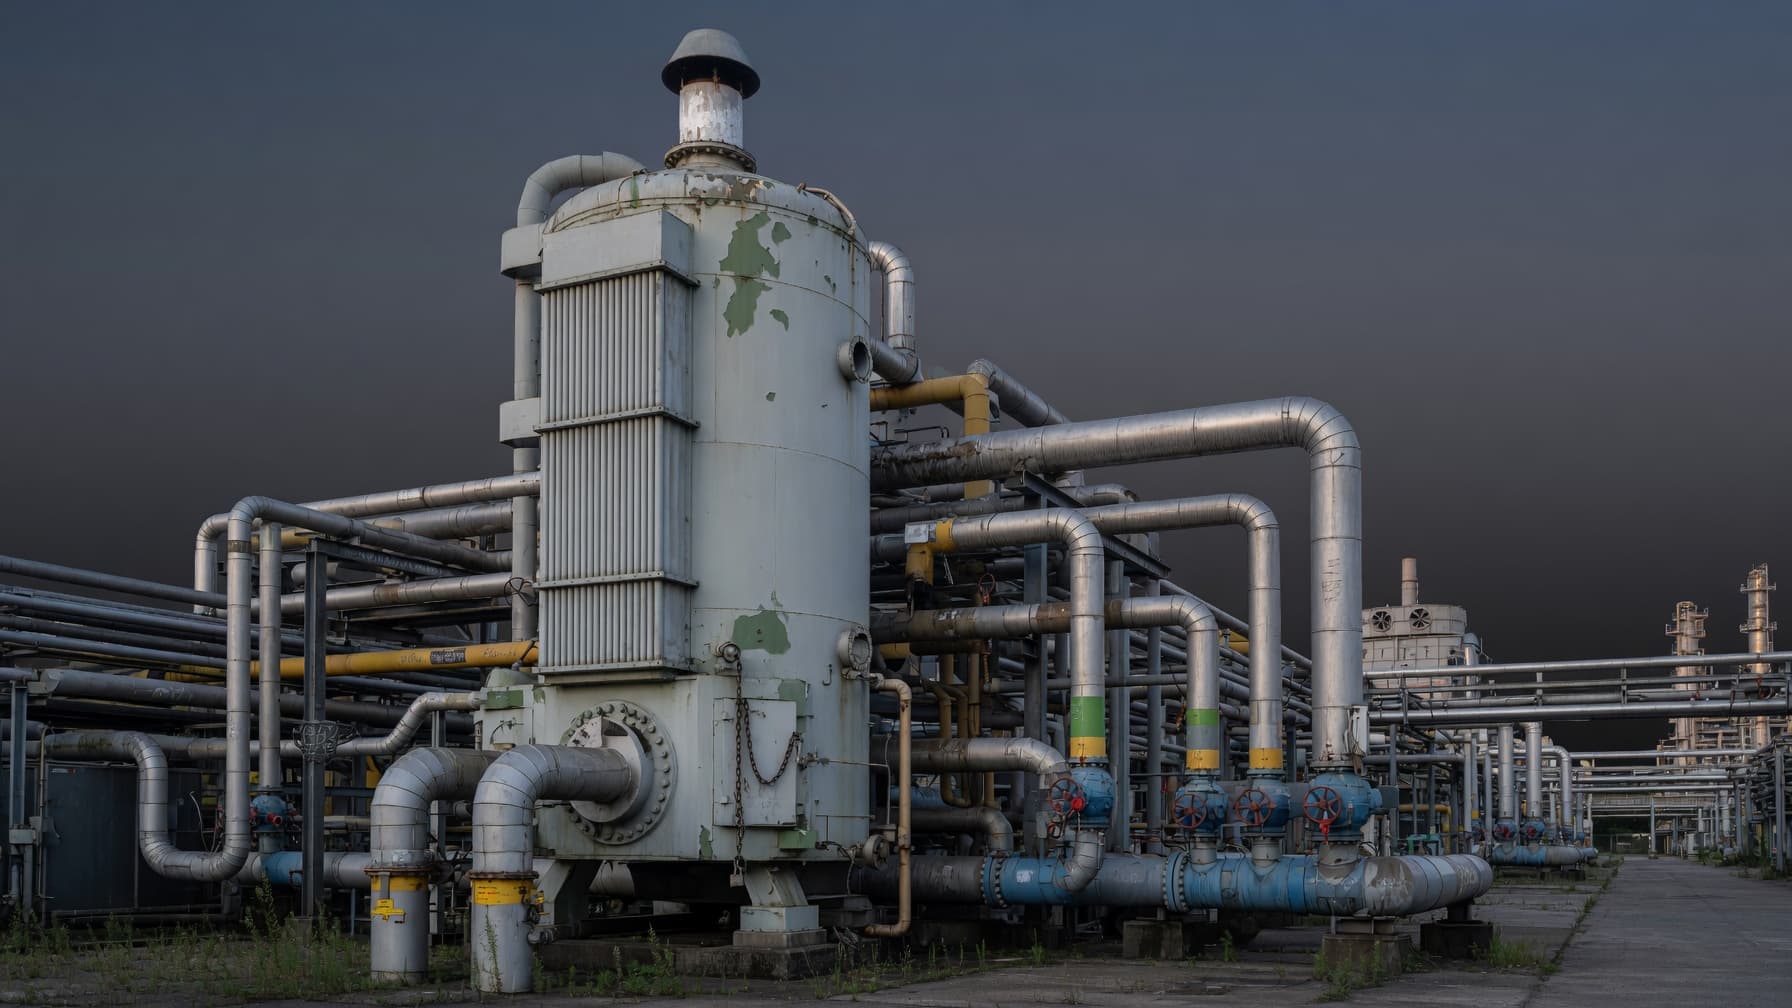
Photo by evening_tao via https://www.freepik.com/
China is On Track to Achieve Significant Increase in Crude Oil Imports in 2023
 In 2023, analysts predict that China will import a record amount of crude oil due to rising gasoline consumption as more people travel as a result of the removal of COVID-19 regulations and the startup of new refineries.
The issue is cited from Reuters in early 2023. China's crude imports may rise by 500,000 to 1 million barrels per day (bpd) or more this year, reaching as high as 11.8 million bpd, experts from four industry consultancies, including Wood Mackenzie, FGE, Energy Aspects, and S&P Global Commodity Insight, say, this would reverse a decline from the previous two years, and breaking the previous record of 10.8 million bpd set in 2020. The four consultancies predicted that Chinese refineries will boost oil throughput by 850,000 Due to growing local demand and appealing export markets, production is expected to climb to 1.2 million bpd over 2022 levels, or 6% to 9%.
Another positive development for the oil market will be the expectation of robust demand from the largest importer in the world, which will add to the support already provided by the OPEC+ producing group's output cutbacks and western sanctions against Russian shipments.
China has seen an increase in demand for gasoline and jet fuel when COVID limits were removed in December. Sun Jianan, an analyst at Energy Aspects, predicted that gasoline and jet fuel would be the main drivers of the increase in demand for liquid fuels. By the end of 2023, Sun predicted that jet fuel usage would be 90% higher than it was before COVID.
As per FGE analyst Mia Geng and Energy Aspects' Sun, the rebound in China's manufacturing and real estate sectors will take longer to manifest, which will slow down demand growth for diesel, a crucial industrial and transportation fuel, and naphtha, a petrochemical feedstock.
Refiners will be encouraged to increase runs in order to maintain profitable export cargoes and deliver more feedstocks to the petrochemical industry, analysts said, in addition to meeting the growing domestic demand.
Industry sources predict that two new PetroChina-owned refineries, Guangdong Petrochemical and Jiangsu Shenghong Petrochemical, with a combined capacity of 520,000 bpd, would begin functioning commercially in the coming months.
According to a corporate source, a third greenfield refinery, the 400,000 bpd Shandong Yulong Petrochemical facility, may start importing crude towards the end of 2023 in preparation for potential test runs.
Experts did list several reasons to be wary of demand projections despite all the favorable elements. External hindrances, such as a bleak outlook for the world economy, would put stress on China's export industry. The potential for a COVID virus return and the uncertainty surrounding China's fuel export policy were listed as additional risks by analysts.
References:
Aizhu, Chen & Xu, Muyu. 2022. China set for record crude oil imports in 2023, analysts say. Reuters.
Photo by evening_tao via https://www.freepik.com/
Related Insights

Tariff Concerns on Canadian Potash Continue to Support US Wholesale Fertilizer Prices
Ongoing concerns over potential tariff actions on Canadian potash imports continue to influence US wholesale fertilizer prices. Procurement professionals should understand how trade policy uncertainty is affecting sourcing decisions, pricing and long-term supply planning.
Europe's Cracker Closures Continue: What the Post-2025 Consolidation Wave Means for Petrochemical Buyers
Europe's petrochemical industry continues to experience cracker closures as producers respond to high energy costs and growing competition from China. Procurement teams should understand how ongoing capacity reductions may reshape regional supply, pricing and long-term sourcing strategies.
Consumer Spending Slowdown Reshapes Demand for Food-Adjacent Chemicals
A slowdown in consumer spending is reshaping demand for food ingredients, preservatives, cosmetic chemicals, and specialty products. Manufacturers must adapt to new consumption patterns and shifting market priorities.
Japan's China Fatigue: Why Chemical Makers Are Redirecting Investment to India
Japanese chemical manufacturers are shifting investment away from China toward India after years of deepening engagement in Chinese markets. The pivot centers particularly on solar materials and reflects broader frustrations with operating conditions in China that procurement teams managing Asian supply chains must understand as sourcing patterns reshape across the region.
Acetic Acid and Ethyl Acetate Tick Up: Why July's Price Increases Matter for Petrochemical Buyers
Modest price increases for acetic acid and ethyl acetate in early July 2026 may signal changing market sentiment in China's petrochemical sector. Procurement teams should monitor these movements closely, as small upstream price adjustments often precede broader changes across downstream chemical markets.
US Petrochemical Plant Shutdowns: What Halts in PS, PVC and Styrene Production Mean for Chemical Buyers
Four major US chemical companies suspended production lines for polystyrene, PVC, styrene and related products during early July 2026. Procurement teams should evaluate how reduced operating capacity may affect product availability, regional pricing and future sourcing strategies.
Don't miss out on our updates! Subscribe to our newsletter now
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.