
Urea (Granular) - Egypt CAS: 57-13-6
Urea (Granular) - Egypt CAS: 57-13-6
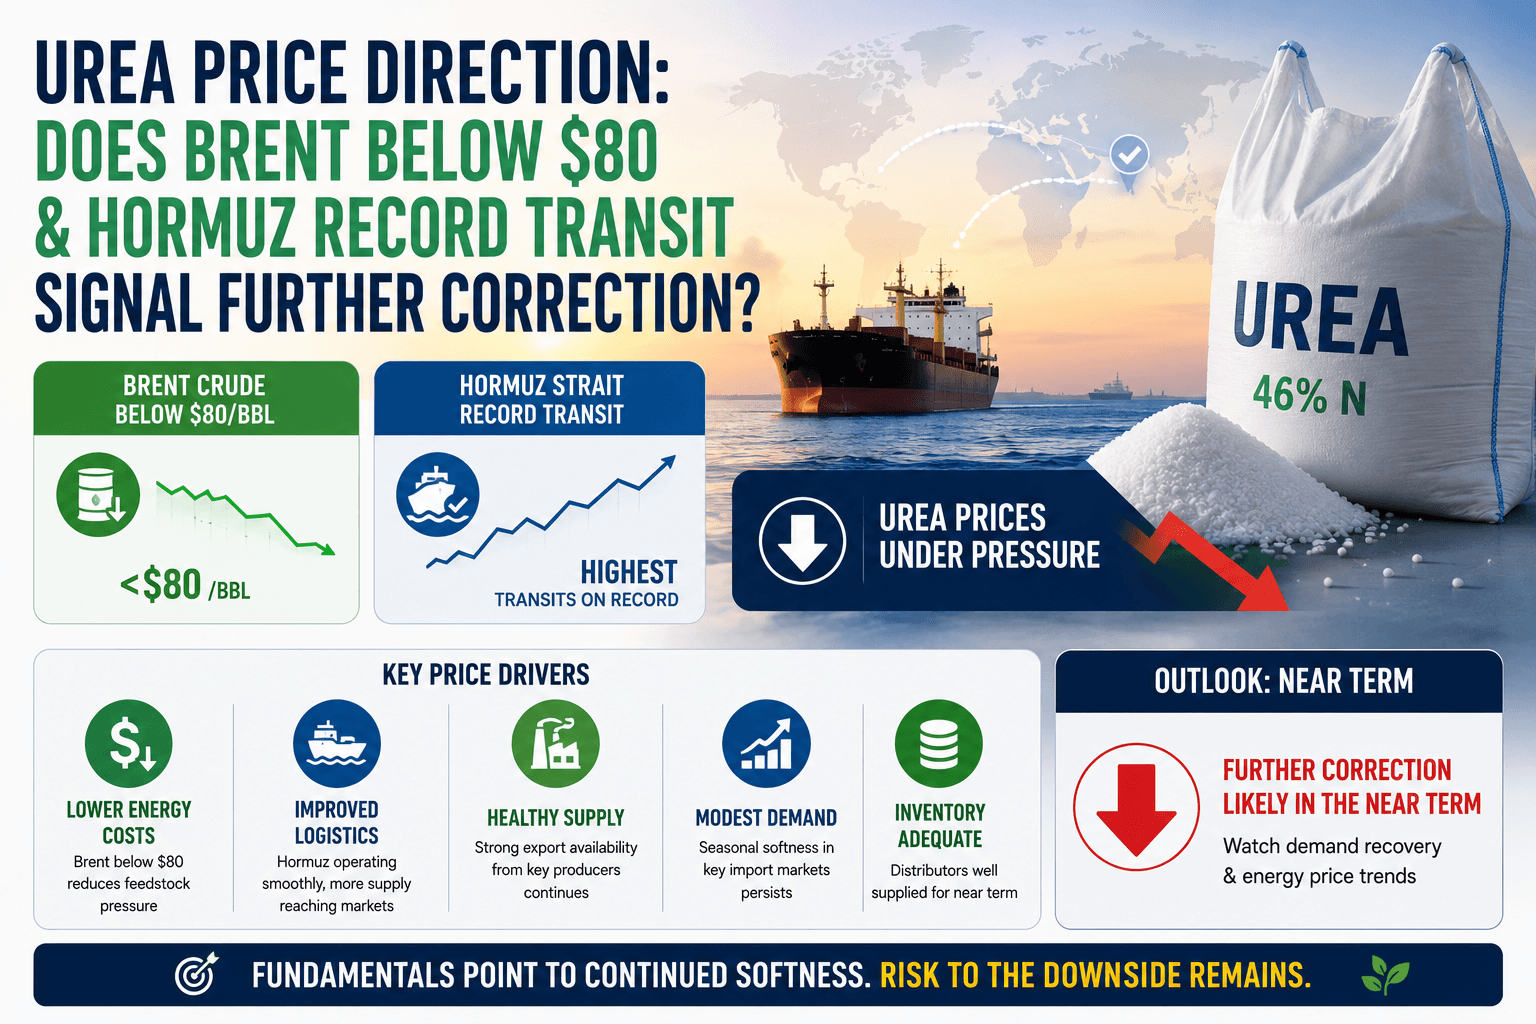
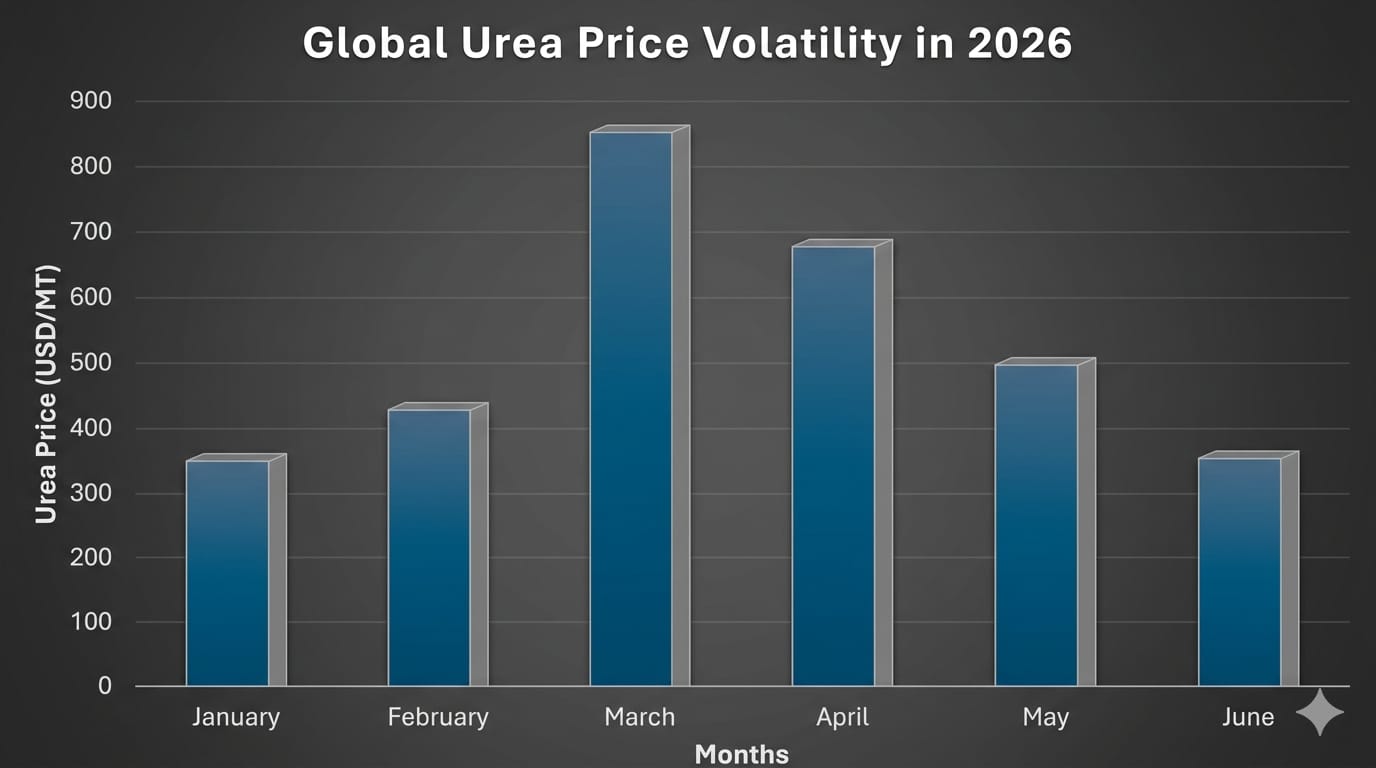
Urea prices have already fallen 36% from April highs, but improving Hormuz shipping and lower Brent crude suggest only modest further correction ahead. For fertilizer buyers, the strongest buying opportunity may already be unfolding before Q3 market stabilization begins.
Formaldehyde producers may finally see feedstock cost pressure ease as methanol supply conditions improve and crude oil prices remain softer. However, buyers of urea-formaldehyde and phenol-formaldehyde resins should not expect immediate price reductions, as contract structures and inventory cycles will delay market adjustments into August 2026.
Urea prices have dropped sharply after the Hormuz MOU, creating potential buying opportunities for fertilizer buyers despite ongoing supply recovery challenges.
Polyethylene markets are entering a new phase as Braskem gradually restores supply following months of allocation controls. While physical availability improves, procurement teams still face uncertainty from pricing volatility, ownership developments and shifting global trade flows.
Methanol pricing outlook for Q3 2026 is entering a new phase as global buyers reassess contracts after Middle East supply concerns begin to ease. Procurement teams need to understand how energy markets, shipping routes and production recovery will influence upcoming methanol negotiations.
The ethanol market is monitoring Australian energy disruptions as Ichthys LNG industrial action creates uncertainty across regional feedstock and energy markets. Buyers are assessing how energy costs, supply stability and production conditions may influence ethanol pricing through H2 2026.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.